What is the retirement spending smile?
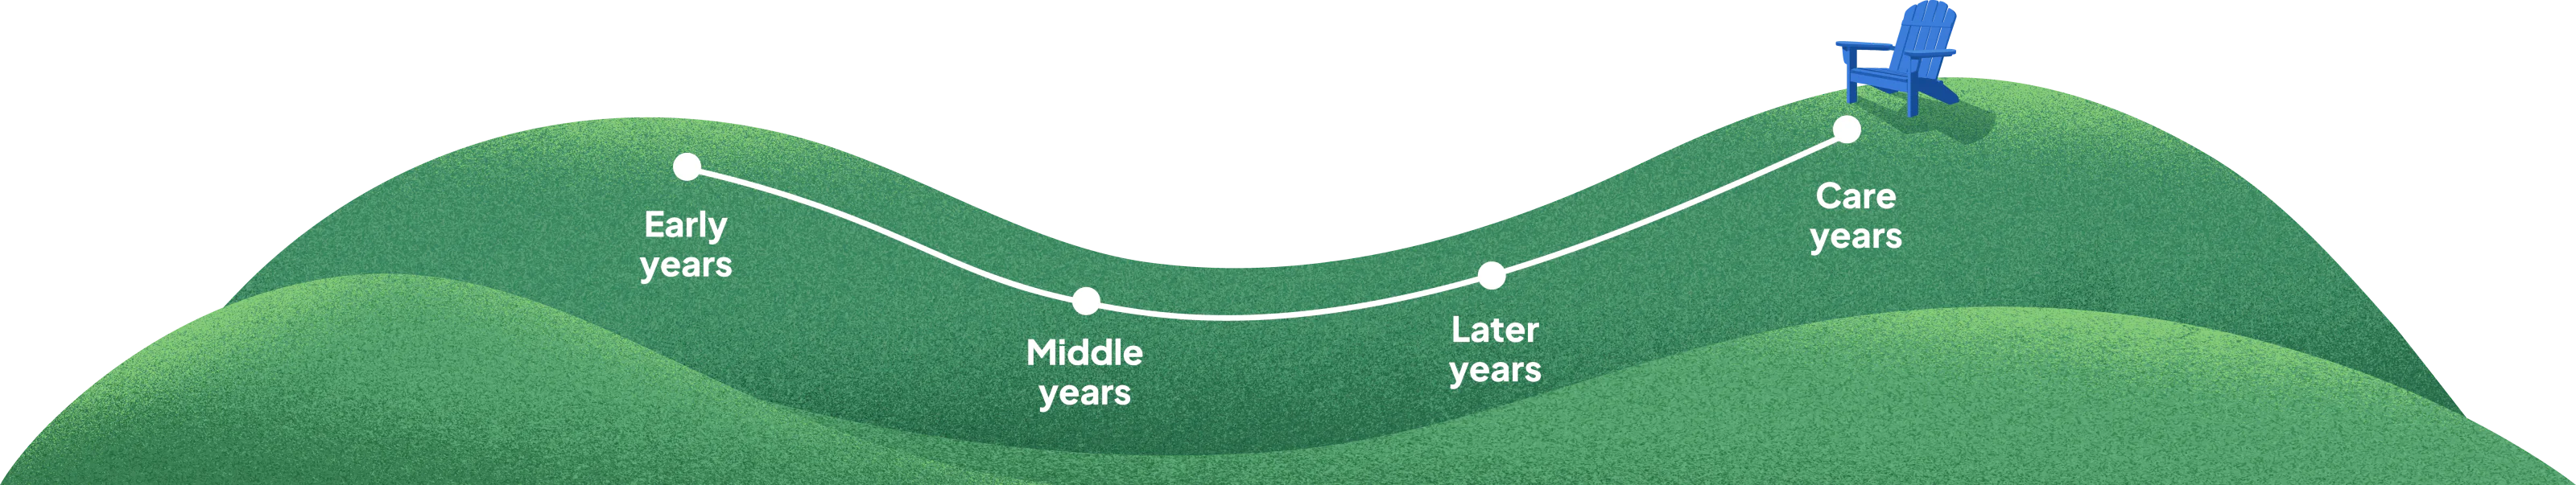
Most retirement rules of thumb assume you will spend the same amount every year, adjusted for inflation, from the day you retire until the end. Real retirees don't. In a 2014 study, Exploring the Retirement Consumption Puzzle, researcher David Blanchett found that households' inflation-adjusted spending tends to fall through most of retirement, then for many households rise again late in life, mostly because of health and care costs. Plotted by age, the curve dips and turns back up, which is why it became known as the retirement spending smile.
This calculator lets you draw your own version of that curve and shows what it means for the one number most people want to know: how much you need saved by the day you retire.
The four phases: early, middle, later and care years
Pasture splits retirement into four phases and lets you set where each one begins and how much you spend in it. Planners have long called the same stretches Go-Go, Slow-Go and No-Go; Pasture adds a Late-Go phase between the last two and gives all four plainer names.
-
Early years (Go-Go)
Usually the most expensive stretch: travel, hobbies, projects you put off while working, and often help for children or grandchildren.
-
Middle years (Slow-Go)
Life slows down and spending usually follows. Long trips give way to shorter ones, and day-to-day costs settle.
-
Later years (Late-Go)
Often the low point of the curve, spent mostly at home and close to family, with discretionary spending at its smallest.
-
Care years (No-Go)
The upturn at the end of the smile. Medical bills, in-home help or assisted living can push spending back up, and Medicare does not cover most long-term care.
Why the shape changes how much you need
The familiar starting point is to save about 25 times one year's spending, the amount a 4% withdrawal would cover. That rule assumes a flat line. If your spending really drops in your seventies and eighties, a flat line overstates the later years, and those are the years your savings have the longest to grow before they're needed. The early years count for more, because that money is spent soon after you retire and has little time to grow first.
So two plans with the same average spending can need very different savings. A plan that spends heavily early and tapers needs more than its average suggests. A plan that holds back early and saves for care costs later needs less. Drawing the curve is how you see which one is yours.
How to use this calculator
- Set your timeline. Enter your retirement age, the age to plan through, and when Social Security starts and roughly how much it would pay per year at 67, your full retirement age, in today's dollars. Starting earlier pays less and starting later pays more, so the calculator adjusts the benefit for the age you choose.
- Shape your spending. Drag each phase's icon up or down to set what you expect to spend each year in that phase. Drag the dashed lines to change the age each phase begins. The line between the icons is smoothed so it reads as a curve; the calculation holds each phase at its icon's level.
- Read the result. The headline figure is the amount you would need invested on the first day of retirement to fund your spending, after Social Security. With a market model it is the median: about half of the starting years tried needed more. The note under the market model gives the best and worst of them, which shows how much the answer swings depending on when you happen to retire.
- Try a different market model. Each model assumes a different average return, so each gives a different answer. Within any one model, the range shown under the selector is sequence-of-returns risk: the same returns, arriving in a different order depending on when you retire.
How the number is worked out
Each year, your spending from the curve minus your Social Security is the gap your savings must cover. Those gaps are discounted back to your retirement age at the market's return, working from the last year back to the first, so a year where Social Security covers more than you spend can be saved toward later years but never counts against earlier ones. The result is what you'd need invested on the first day of retirement. Everything is in today's dollars, so Social Security and spending both keep pace with inflation and the numbers stay comparable to your paycheck now.
Each year's spending comes out at the start of that year and what's left grows through it, and the plan runs to the end of the age you plan through: 31 years for 62 to 92.
Markets don't return the same thing every year, so the calculator doesn't pretend they do. With a market model, your plan is run from every possible starting year in that model's sequence of returns, and the headline is the median of those runs. Historical uses the S&P 500's actual returns from 1934 to 2024, so each run is a real retirement date. Conservative, Moderate and Optimistic are illustrative sequences built by Pasture, with good and bad years mixed in around a lower or higher average. Flat is there if you'd rather assume one steady rate. The runs overlap, so they are not independent trials, and retirements too recent to have lasted the whole plan aren't included. This is a planning illustration, not financial advice.
What this calculator leaves out
It's built to answer one question quickly, so it leaves a lot out. It doesn't model income taxes, Required Minimum Distributions, the split between pre-tax, Roth and taxable accounts, healthcare before Medicare at 65, a spouse's benefits, pensions, or one-off costs like a new roof. All of those can move the answer a long way. The Historical model also assumes every dollar sits in the S&P 500 with no fees, which is bolder than most retirees invest.
Pasture takes the same spending curve and runs it year by year against your actual accounts, Social Security, taxes, healthcare premiums and withdrawal order, so you can see whether your whole plan supports it.
Frequently asked questions
No. It describes a common pattern across many households, not a rule. Some people spend steadily for decades. Others never see the late-life rise because they have long-term care insurance, family support or good health. That's why every point on the curve here can be moved.
They're the traditional names for the stages of retirement by activity level: Go-Go for the active early years, Slow-Go as things quiet down, and No-Go when health limits what you do. Pasture uses four phases with plainer names — the early years (Go-Go), middle years (Slow-Go), later years (Late-Go) and care years (No-Go).
Yes. Everything is in today's dollars. Spending, Social Security and returns are all measured after inflation, so the figures compare directly with what things cost now.
The 4% rule starts from a savings balance and works out a flat, inflation-adjusted withdrawal. This calculator works the other way. It starts from the spending you expect in each phase and works out the savings needed to fund it.
No. It's a planning illustration to help you think about the shape of your spending. For decisions about your own money, consider a fee-only financial planner.